

· AFX Research
A Marital Home With VA or USDA Financing, What a Divorce Changes
A quitclaim moves the deed and does nothing to the loan. For a veteran it also leaves entitlement tied up, which can block buying again for years.
Table of Contents
A veteran and their spouse divorce. The decree awards the house to the spouse, a quitclaim deed is signed and recorded the same week, and everybody considers the property settled. Two years later the veteran tries to buy a home of their own and discovers that their VA entitlement is still tied to a loan on a house they no longer own, that they remain liable on that loan, and that nothing in the decree changed either fact. The deed moved. The loan did not. This is the sharpest version of the gap described in the divorce decree versus the deed.
What these loans add
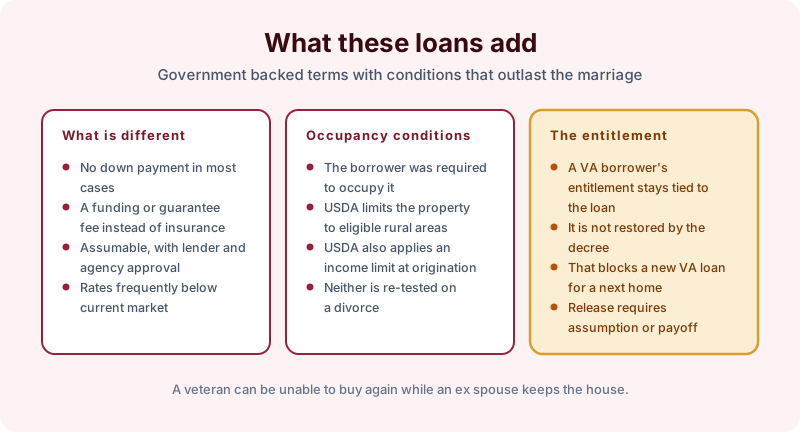
What is different about them is mostly favorable. No down payment in most cases. A funding or guarantee fee in place of mortgage insurance. Assumability, with lender and agency approval. And on an older loan, a rate well below anything currently available, which is itself a marital asset worth preserving.
The occupancy conditions came with origination. The borrower was required to occupy the property. USDA loans additionally require an eligible rural location and applied an income limit when the loan was made. Neither condition is re-tested because of a divorce, which is useful to know when somebody worries that separating will trigger something.
The entitlement is the part that surprises people. A VA borrower’s entitlement stays attached to the loan until it is paid off or formally assumed by another eligible veteran with a release of liability. A decree does not restore it, a quitclaim does not restore it, and until it is released the veteran’s ability to use a VA loan for a next home is limited or gone entirely.
What the record shows
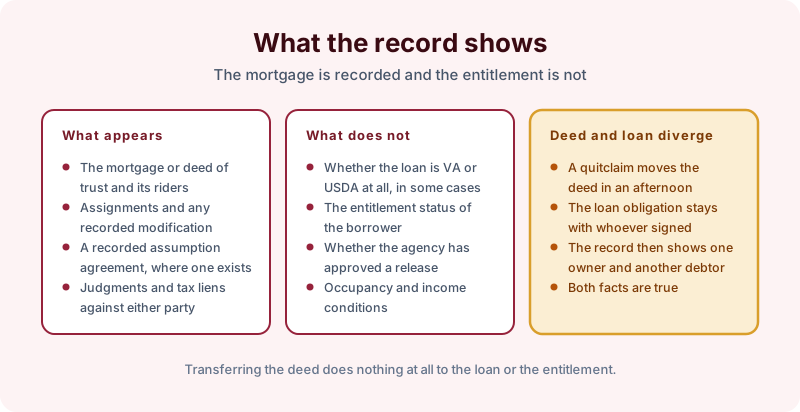
What appears is the mortgage or deed of trust with its riders, the assignments and any recorded modification, a recorded assumption agreement where one was executed, and the judgments and tax liens against either party.
What does not appear is frequently the decisive material. Whether the loan is VA or USDA at all may not be obvious from the recorded instrument. The entitlement status of the borrower is an agency record. Whether a release of liability has been approved is not recorded. The occupancy and income conditions live in the origination file.
So the record will show you one owner and, if you read it carefully, a different debtor, and both facts are accurate. A quitclaim takes an afternoon and the loan obligation stays exactly where it was.
What actually resolves it
Three routes, and only two of them work.
A qualified assumption with release of liability. The spouse keeping the house assumes the loan with lender and agency approval, and the departing spouse applies separately for release of liability. On a VA loan, entitlement is only restored where the assuming party is an eligible veteran substituting their own entitlement. The release is a distinct application and is frequently forgotten.
A refinance. Pays off the loan, frees the entitlement, and loses the rate, which on an older loan can be an expensive trade. The alternative is weighed in assuming the mortgage instead of refinancing.
A quitclaim alone. Changes nothing about the debt or the entitlement, and it is what most settlements actually do. That is the same mismatch as in one spouse on the deed, both on the mortgage.
Scoping the search
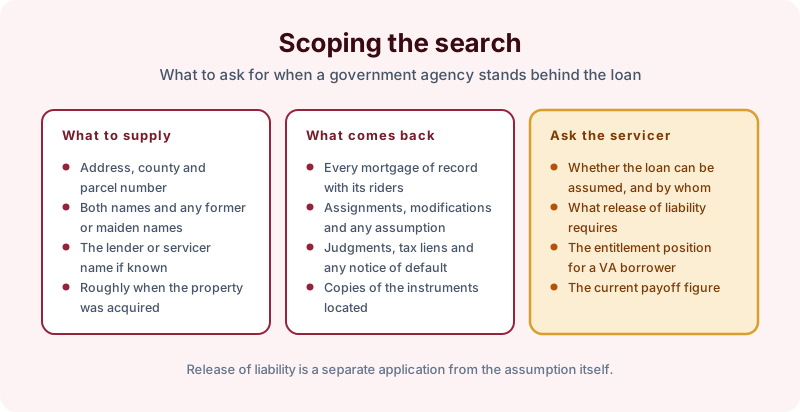
Give us the address, county and parcel number, both names with any former or maiden names, the lender or servicer name if known, and roughly when the property was acquired. What comes back is every mortgage of record with its riders, the assignments, modifications and any assumption, the judgments, tax liens and any notice of default, and copies of the instruments.
Ask the servicer whether the loan can be assumed and by whom, what release of liability requires, the entitlement position for a VA borrower, and the current payoff.
The takeaway
On a government backed loan the deed and the debt come apart easily and the entitlement comes apart from neither. Settle the assumption and the release of liability in the decree rather than leaving a quitclaim to do work it cannot do. Start the order online, or send us the address and the names and we will tell you what a search of that scope would and would not cover before anything is ordered.