

· AFX Research
A Marital Home With a PACE Assessment on It, What to Check
It was financed as an improvement and is collected as a property tax, it outranks the mortgage in many states, and it is not on any payoff statement.
Table of Contents
A couple divorcing after sixteen years have $140,000 of equity in the house, or they do until somebody reads the tax bill properly. Four years ago they financed a solar array and new windows through a PACE program, and $31,000 of that obligation is still outstanding. It is not a mortgage, it does not appear on the mortgage payoff statement, and in their state it sits ahead of the mortgage in priority. The equity number everybody has been working from is wrong by a third. This is the same category of surprise as solar panel leases and liens on the marital home, with a senior position attached.
What a PACE assessment is
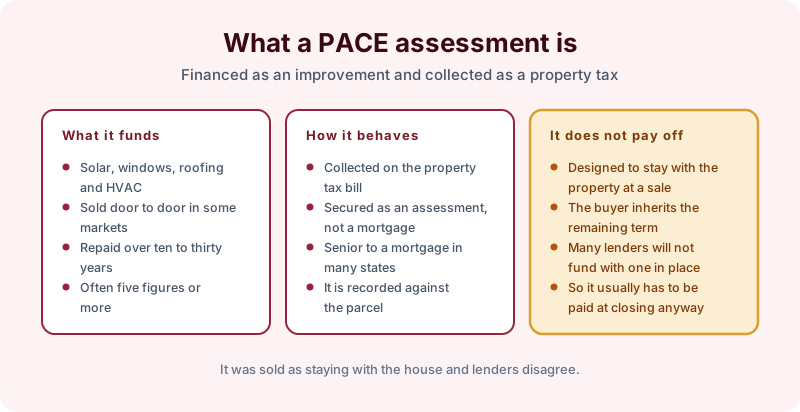
Property Assessed Clean Energy financing funds improvements — solar, windows, roofing, HVAC — and is repaid over ten to thirty years. In several markets it has been sold door to door, which is relevant to how carefully anybody read the paperwork.
How it behaves is the unusual part. It is collected on the property tax bill, secured as an assessment rather than as a mortgage, and in many states it takes priority over an existing mortgage by operation of law. It is recorded against the parcel, so a search finds it, provided somebody is looking for an assessment rather than for a lien.
It was designed not to pay off at a sale. The structure assumes the obligation stays with the property and the next owner inherits the remaining term, which was the selling point. In practice a great many mortgage lenders decline to fund a purchase or refinance with one in place, so it usually has to be cleared at closing after all.
What it does to a buyout
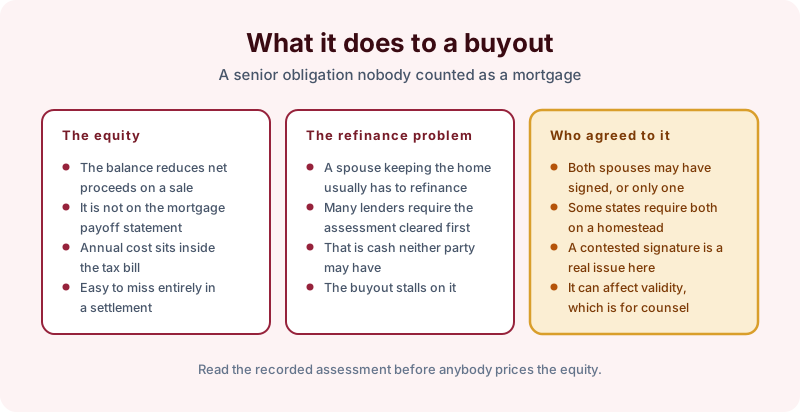
The equity effect is direct. The balance reduces net proceeds on a sale, it is absent from the mortgage payoff statement, and the annual cost is buried inside a tax bill that most settlements treat as a single number. It is genuinely easy to miss.
The refinance problem is worse. A spouse keeping the house normally has to refinance to remove the other from the loan, and where the new lender requires the assessment cleared first, that is cash neither party necessarily has. The buyout stalls on an obligation nobody included in the negotiation.
And there is a question about consent. Both spouses may have signed, or only one may have. Several states require both signatures to encumber a homestead, which is the rule discussed in homestead and spousal rights, and a contested signature on a PACE contract raises a validity question that belongs to counsel.
Why the tax bill hides it
Because it arrives as one figure. A homeowner sees the annual property tax go up by $2,800 and attributes it to assessment increases, and a settlement using “the property taxes” as a line item has absorbed the assessment without identifying it.
The way to see it is to look at the itemized bill rather than the total, and to search the record for the recorded assessment contract. Recording practice varies by county and the programs differ by state, so nothing about how a neighbor’s situation resolved should be assumed to transfer.
Scoping the search
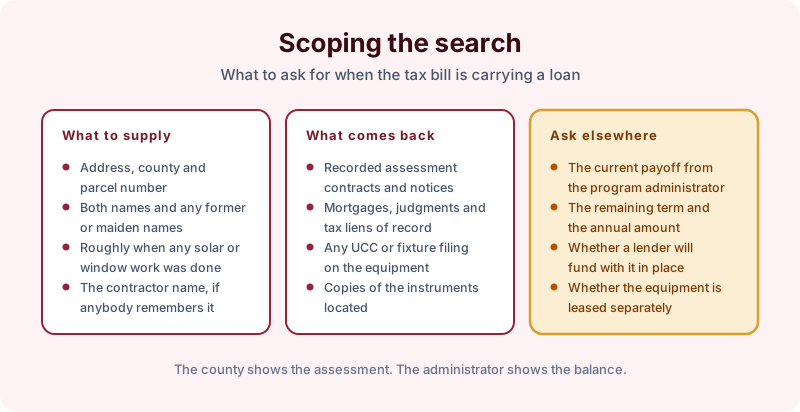
Supply the address, county and parcel number, both names with any former or maiden names, roughly when any solar or window work was done, and the contractor name if anybody remembers it. What comes back is the recorded assessment contracts and notices, the mortgages, judgments and tax liens of record, any UCC or fixture filing on the equipment, and copies of the instruments located. Our process page sets out how that is done.
Ask the program administrator for the current payoff, the remaining term and the annual amount, and ask a lender whether they will fund with it in place. A records search reports what was recorded and indexed over the term searched, and an empty result does not establish that nothing is owed.
The takeaway
A PACE assessment is a senior obligation that looks like a tax, hides inside a tax bill and does not appear on a mortgage payoff. Find it before the equity is agreed, because it changes the number and may block the refinance the settlement depends on. Start the order online, or send us the address and the names and we will tell you what a search of that scope would and would not cover before anything is ordered.